
You don't need an ultra-complex strategy to invest well. In this article, discover how to invest 1200 CHF per month with a diversified, passive, and automated approach, while maintaining simple and effective management.
Recommended products


Introduction
After sharing a simplified strategy for investing 1200 CHF per month, I now wish to offer a version more diverse, while remaining true to an approach passive, simple, automatable and suitable for the long term.
The goal is not to maximize returns at all costs, but to build a portfolio balanced, resilient and easy to manage (less than 5 minutes per month).
⚠️ Before reading this article
This article does not constitute investment advice. This is an example based on my research and personal opinion.
All investments carry risks., including capital loss. Before investing, make sure you have:
- A emergency reserve (3 to 6 months of expenses).
- Pay off your expensive debts (consumer loans, credit cards, etc.).
⚠️ The Past performance is not indicative of future results. The results announced cover the period from August 2016 to 2026. However, these results do not predict the future.
Investing with a diversified strategy
A diversified strategy doesn't mean owning dozens of ETFs or individual stocks. The idea is to cover several asset classes to reduce risks while maintaining a perspective of long-term growth.
With only 6 placements, It is possible to gain global exposure by:
- The shares (developed and emerging markets)
- Real estate (Global REITs)
- The obligations (global)
- Raw materials (gold, metals, energy)
- Gold (safe haven asset)
How to invest 1200 CHF per month?
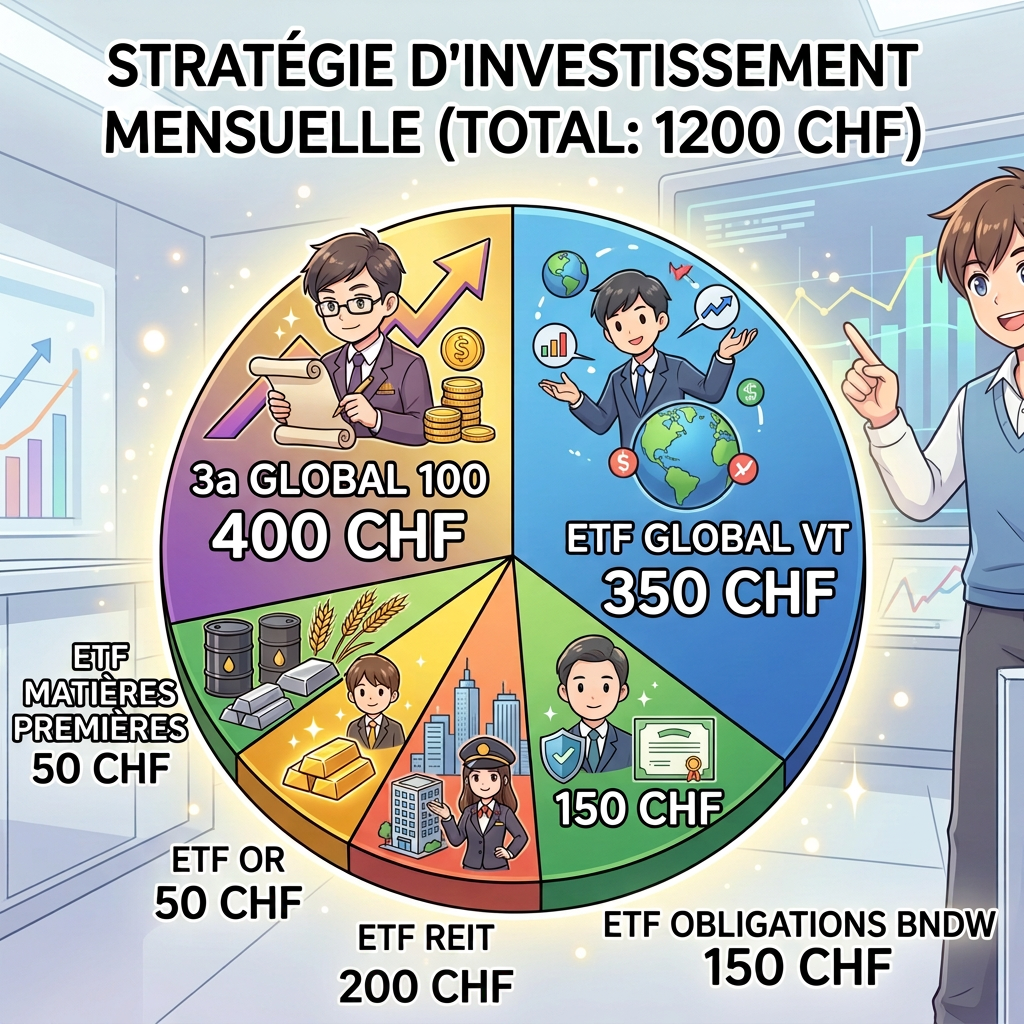
| Amount | Investment type | Objective | Example of a product |
|---|---|---|---|
| 400 CHF | Pillar 3a invested in stocks | Growth + tax advantage | VIAC Global 100* / Finpension Global 100* |
| 350 CHF | Global Equity ETF | Long-term growth | VT (Vanguard Total World)* |
| 200 CHF | Global real estate ETF (REIT) | Passive income + diversification | REET (iShares Global REIT)* |
| 150 CHF | global bond ETF | Portfolio stabilization | BNDW (Vanguard Total World Bond)* |
| 50 CHF | Commodities ETF | Inflation protection | Invesco Bloomberg Commodity UCITS ETF* |
| 50 CHF | ETF or physical | Safe haven | Xetra-Gold (physical gold)* |

Breakdown by asset class
- 62.5% (750 CHF) : Growth (actions + 3a)
- 16.5% (200 CHF) : Global passive real estate (Global REIT ETF)
- 21% (250 CHF) : Stabilization and diversification (bonds, commodities and gold)
400 CHF: Pillar 3a invested in equities (Global 100)

Why invest in a 3a global 100?
- Tax advantage Payments in 3a are tax-deductible in Switzerland.
- Long-term growth A strategy like: Global 100 (VIAC or Finpension) invests 99% in global equities, with a strong exposure to developed and emerging markets.
- Passive management No need to monitor the markets, everything is automated.
- Acceptable fees for a 3a : ~0,40%
Historical performance:
- Annualized return over 10 years: ~8% (source: VIAC Global 100).
350 CHF: Global Equity ETF (VT)

Why invest in a global ETF?
- Maximum diversification : VT covers more than 95% of global stocks (developed + emerging countries).
- Simplicity : A single ETF to access thousands of companies in many countries (Apple, Microsoft, Nestlé, etc.).
- Reduced fees VT has fees of 0,07% per year.
Historical performance (for information purposes only):
- Annualized return over 10 years: ~12% (dividends reinvested).
- ⚠️ Equity markets can be volatile in the short term.
200 CHF: Global real estate ETF (REIT)

Why invest in passive real estate?
- Exposure to real estate without buying a property REITs (Real Estate Investment Trusts) allow investment in real estate. residential, commercial, industrial, etc. Worldwide.
- Passive income Some REIT ETFs pay out quarterly dividends (average yield: ~3.5%).
- Liquidity Unlike a physical property, a REIT ETF is easy to buy/sell.
Example of an ETF:
- REET (iShares Global REIT): Global diversification, fees 0,14%.
Historical performance:
- Annualized return over 10 years: ~4% (with dividends reinvested)
150 CHF: Global Bond ETF (BNDW)

Why invest in a global bond ETF?
- Portfolio stabilization The obligations are less volatile than the shares.
- Regular income BNDW distributes monthly coupons (dividends) (average yield: ~2.5%).
- Global diversification : Exposure to government and corporate bonds worldwide.
Example of an ETF:
- BNDW (Vanguard Total World Bond): Fees 0,09%.
Historical performance (for information purposes only):
- Annualized return over 10 years: ~2,5% (dividends included).
50 CHF: Commodity ETF

Why a commodities ETF?
- Inflation protection Raw materials (gold, oil, metals, agriculture) tend to to gain value during periods of inflation.
- Additional diversification Raw materials have a weak correlation with stocks and bonds.
Example of an ETF:
- Invesco Bloomberg Commodity UCITS ETF Broad diversification (energy, metals, agriculture), operating costs 0,19%.
historical performances :
- Annualized return over 10 years: ~1-3% (variable depending on economic cycles).
50 CHF: Physical gold (Xetra-Gold)

Why a Gold ETF?
- Safe haven Gold is traditionally considered a safe active in times of crisis.
- Protection against systemic risks In the event of a stock market crash or monetary crisis, gold can stabilize the portfolio.
- Liquidity Physical gold (via Xetra-Gold) is easy to buy/sell like an action.
Example product:
- Xetra-Gold Physical gold stored in France, fees of 0,15% per year.
Historical performance:
- Annualized return over 10 years: ~2% (Gold does not generate income; its value depends on supply and demand).
Strategy Summary
With 6 placements, This portfolio offers:
- Global diversification (stocks, real estate, bonds, commodities and gold).
- A good investment base in Switzerland and CHF (approximately 20% of the portfolio)
- Passive 100% management (no need to follow the markets).
- Regular passive income (REIT dividends and bonds).
- A little protection against inflation (raw materials + gold).
- A tax advantage (via 3a).
| Amount | Investment | Asset class | Main objective | Dividend frequency |
|---|---|---|---|---|
| 400 CHF | 3a Global 100 | Global Actions | Growth + tax advantage | / |
| 350 CHF | ETF VT | Global Actions | Growth | Quarterly |
| 200 CHF | ETF REET | Global Real Estate (REIT) | Quarterly revenues | Quarterly |
| 150 CHF | ETF BNDW | Global Bonds | Stabilization + monthly income | Monthly |
| 50 CHF | Commodities ETF | Raw materials | Inflation protection | / |
| 50 CHF | Xetra-Gold | Physical gold | Safe haven | / |

📊 Estimated portfolio return (2015-2025)
Investing 1200 CHF per month, diversified monthly investment, monthly investment strategy, how to invest 1200 CHF, Swiss diversified investment, ETFs for beginners, balanced portfolio 1200 CHF, investing in stocks and bonds, monthly wealth management, best allocation 1200 CHF, passive investment 1200 CHF, optimized return 1200 CHF, tips for investing each month, diversification on a small budget, investing in Switzerland with 1200 CHF
Here is an estimate of the annualized return of each asset over 10 years (August 2016-2026):
- 3a Global 100 : ~8%
- ETF VT : ~12%
- ETF REET : ~4%
- ETF BNDW : ~2,5%
- Commodities ETF : ~2%
- Gold (Xetra-Gold) : ~2%
Average annualized portfolio return for the period 2016-2026: ~7% per year (dividends reinvested).
Regarding fees, without accounting for taxes and with an economical stock market account, the total fees for this portfolio are approximately 0.30% per year.
In my opinion, it's a good performance considering the costs and very simple management.
To give an example: If you had invested 50,000 CHF 10 years ago + 1200 CHF / month, this portfolio would be worth today ~350,000 CHF (estimate based on historical returns).
⚠️ This return is an estimate based on past performance and does not guarantee future performance.
A simple strategy rather than a perfect strategy
As he said John Bogle (founder of Vanguard):
«"The main enemy of a good plan is the dream of a perfect plan. Be content with the good plan."»
This wallet is not not perfect, but it is:
- Sufficiently diverse to limit the risks.
- Easy to manage (5 minutes per month).
- Suitable for passive, long-term investment.
I prefer to spend 5 minutes a month and sleep soundly knowing my investments are sound, rather than spending 2 hours a day for a "potential" perfect return.
FAQ: How to invest 1200 CHF – Diversified version
Why is the annualized return of this portfolio estimated at ~7% per year?
This portfolio combines:
- Global actions (high historical return, but volatile).
- REITs and bonds (stable income, but lower return).
- Raw materials and gold (protection against inflation and crises).
There weighting of these assets allows us to estimate an average return of 7% per year in the long term. However, this past performance is not guaranteed and depends on future economic conditions.
What are the main risks of this portfolio?
- Stock volatility The CHF 750 invested in shares (3a + VT) can decrease by 20-30% in the event of a stock market crash.
- Interest rate risk : Bonds (BNDW) can lose value if rates rise.
- Liquidity risk REITs and commodities can be less liquid than the shares.
- Exchange rate risk USD-denominated ETFs (VT, REET, BNDW) are exposed to fluctuations of the Swiss franc (CHF).
How can volatility be reduced without sacrificing too much return?
To reduce volatility, you can:
- Increase the share of bonds (e.g., going from 150 CHF to 200 CHF).
- Add cash (e.g., keep 50 CHF in cash each month).
- Slightly reduce the share of shares (e.g., going from 750 CHF to 600 CHF).
⚠️ Attention A reduction in volatility may decrease long-term yield.
Should this portfolio be rebalanced regularly?
Yes, it is recommended to rebalance twice a year For maintain the initial distribution (e.g., if stocks rise sharply, their share in the portfolio will increase).
However, don't stress if an asset is too high.
For example, if you find that you have too much REIT, stop putting money into your REIT ETF and put your next payments into the ETF that has too low a percentage.
What taxes apply in Switzerland?
In Switzerland, taxation depends on your canton of residence. Here are the general rules:
- 3a : The gains are not taxable. as long as the funds are not withdrawn. Upon withdrawal, they are taxed as a income (rate varies depending on the canton).
- ETFs (excluding 3a) :
- Dividends Taxable as income (rate varies depending on the canton).
- Capital gains : Not taxable in Switzerland (unless you are considered a professional trader).
- Physical gold (Xetra-Gold) :
- Not taxable if held for more than 6 months (considered as a investment good).
- Taxable if sold before 6 months (considered as a speculation).
➡ Advice For tax optimization, consult a Swiss chartered accountant.
How to invest 1200 CHF – Diversified version
Subscribe for the latest news ✍
You have a frugalist or minimalist project and you want a training? Click ”here”.
My pages
- About me
- Saving / Frugalism
- Blog
- Shop
- Contact
- Training and E-book
- Invest
- Minimalism
- My account
- Newsletter
- Basket
- Order confirmation
Lastest Post
- After 10 years of investing in ETFs: which ETF would I choose?
- Financial freedom: why the first 100,000 are the hardest
- The best advice in the world to save
- The Neon bank, the summary
- How does digitalization influence minimalist?
How does this blog live?
Overall, this blog lives on sharing a frugal and minimalist lifestyle.
For a question of transparency towards the readers. All recommended products are in order to make life cheaper, simpler and to promote the essentials.
Basically, my only income with this blog comes:
- Training courses that I provide
- Promo codes for the products I use
- Donations that readers make in exchange for neutral information.
About me
I decided to create this blog to develop and help readers who are looking for a simpler and more economical life.
Compared to before, I was a person who consumed a lot until the day I realized that my consumption made me sadder and poorer 😑
Now I prefer the minimum of my needs to be happy and achieve my financial freedom.
Without realizingI started to focus on saving and investing to depend on a boss for as little time as possible and to speed up my personal projects.
As a result, I am getting richer in a way that I never imagined since I have an average salary in Switzerland.
What is the purpose of this blog?
The goal is to share and learn with others who seek freedom and simplicity 😉
Are you rather minimalist or frugal Jonny?
I am as minimalist as I am frugalist. However, there are situations where I lean more towards an art of life.
To conclude, I think the most important thing is to feel comfortable in your lifestyle 😊
How to invest 1200 CHF – Diversified version
How to invest 1200 CHF – Diversified version
Leave a Reply